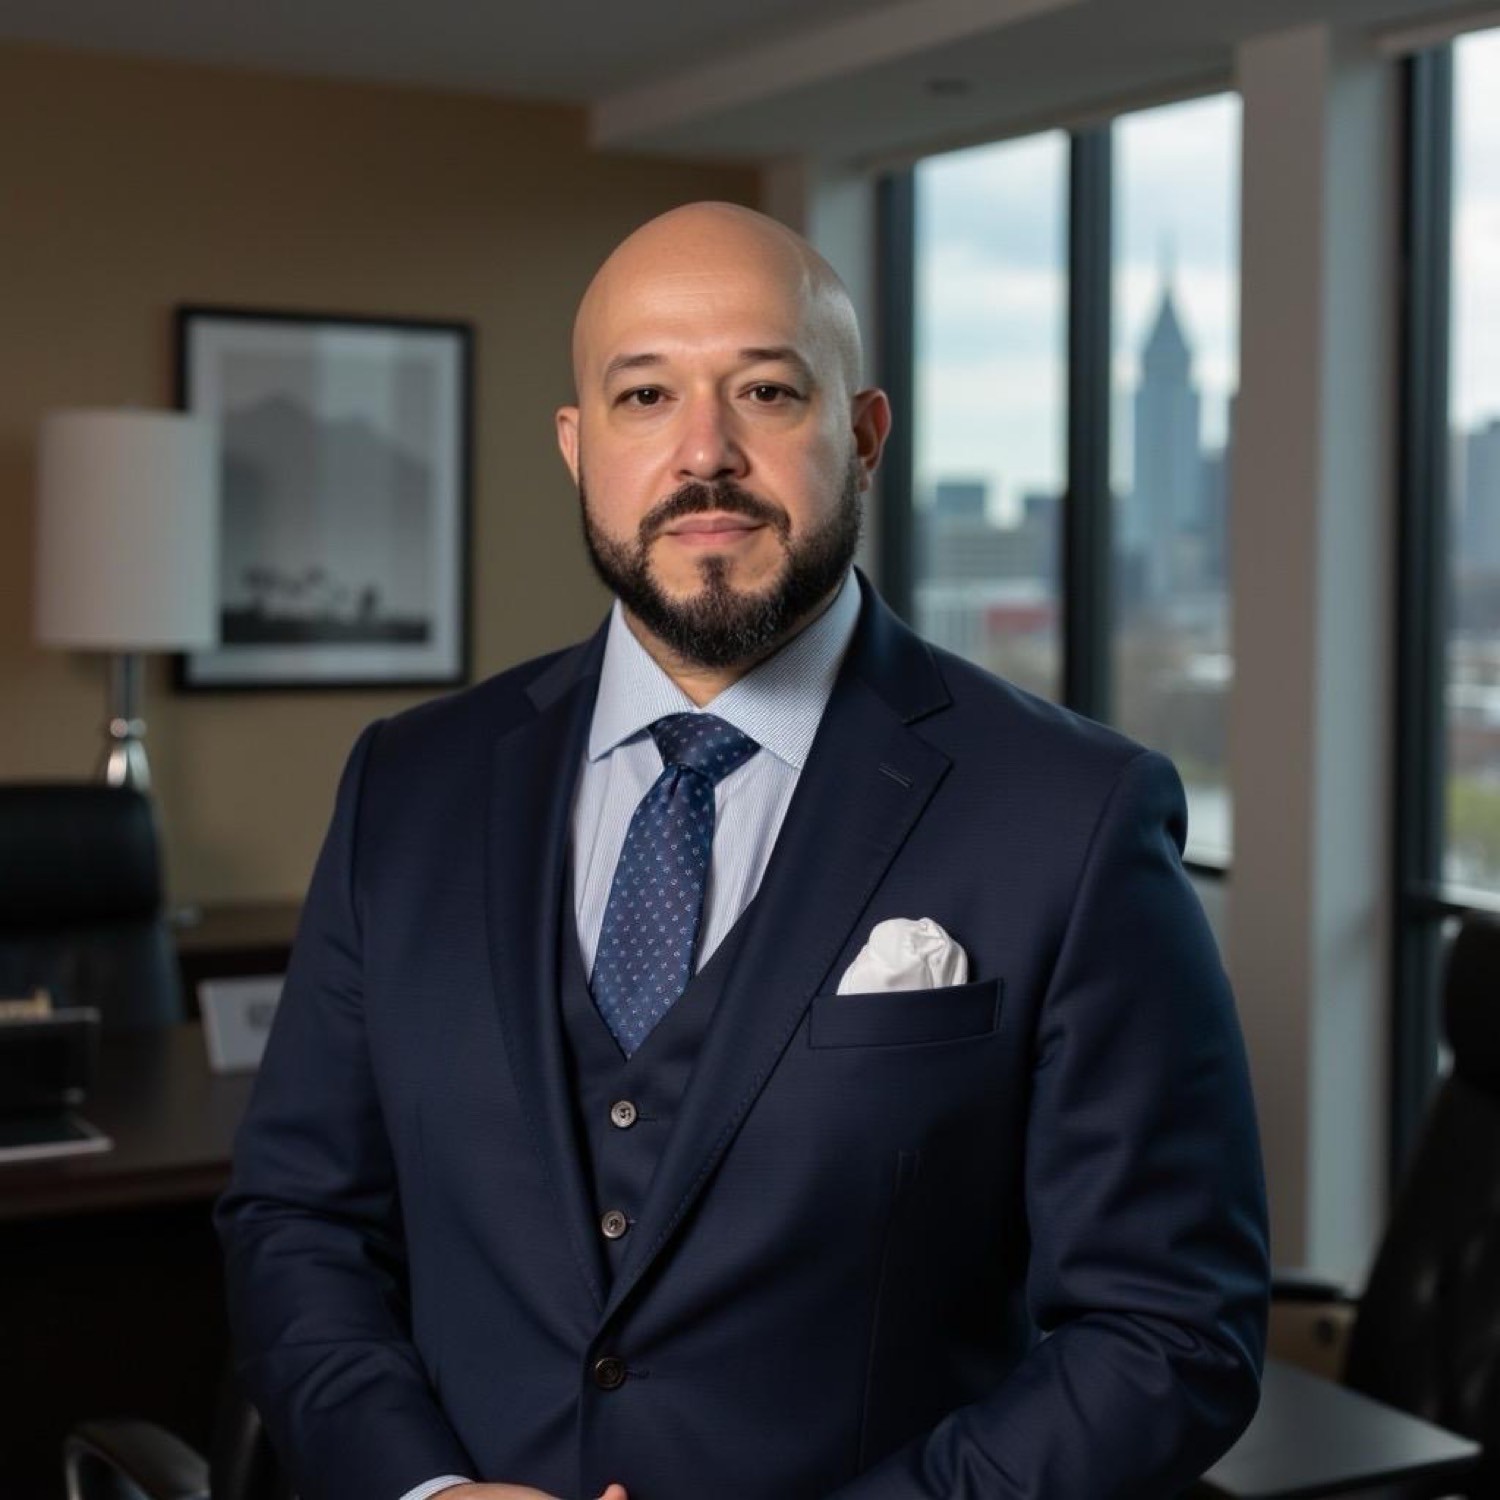
Ivan Duarte wearing a navy three-piece suit, light blue shirt, and blue tie, with a city skyline behind him

Ivan Duarte, The Mortgage Architect

Ivan Duarte

VP of Mortgage Lending

CrossCountry Mortgage, LLC NMLS3029

NMLS #32559

Meet the person behind the plan

Let's design your plan together.

Ivan Duarte, The Mortgage Architect. NMLS #32559.

Buying a home for the first time is one of the biggest decisions you'll ever make, and you shouldn't have to figure it out alone. I help first-time homebuyers navigate the entire process, from understanding credit and budgeting to choosing the loan that fits. I work with FHA loans, conventional loans, and housing finance agency programs that offer low down payment options and down payment assistance, so you can get into a home with less cash upfront than you might expect.

Read my story

If you're ready for your first investment property, I specialize in helping first-time investors get started. DSCR loans let you qualify based on the property's rental income rather than your personal income, which opens doors for self-employed buyers and anyone whose income doesn't show up neatly on a W-2. I also work with conventional investment loans and other products designed for building a rental portfolio from the ground up.

Self-employed borrowers get turned down constantly because lenders only want to see tax returns. Bank statement loans solve that by qualifying you on twelve to twenty-four months of personal or business bank deposits instead. P&L loans use a prepared profit-and-loss statement, and VOE loans verify income directly with your employer when traditional documentation falls short. If another lender said no, there's a good chance one of these is the path that works.

Whether your goal is homeownership or your first rental, the approach is the same: clear explanations, real options, and a loan structured around your situation, not a one-size-fits-all product. Ready to talk about what's possible for you?

Ivan Duarte
VP of Mortgage Lending
Book a call (opens in a new tab)

Different goals. Thoughtful financing.

A first home and an investment property call for different conversations. Start with guidance that fits your goals.

DSCR & investment properties

Explore financing that considers a property's rental cash flow, with a plan for the investment you have in mind.

Learn more: DSCR & investment properties

1–4 unit properties, short-term and long-term rentals, and portfolio growth. Program eligibility and requirements vary.

Foreign national financing

Buying U.S. property while living abroad starts with understanding your financing options and the documentation involved.

Learn more: Foreign national financing

Guidance for non-U.S. residents, from an initial conversation through assembling the required documents.

Your first home

Make room for questions. Get step-by-step guidance as you learn the process and consider your options.

Learn more: Your first home

Down payment assistance programs may be available. Eligibility, program requirements, and availability vary.

In your language

Talk through the details in English or Spanish, with time to understand the choices in front of you.

Learn more: In your language

Bilingual service from the first conversation to the next step in your plan.

Loan programs I work with.

Different goals call for different financing. Here is the range of programs we can explore together, from a first home to a growing rental portfolio.

Buying a home

  • Conventional loans
  • FHA loans
  • VA loans
  • USDA loans
  • Jumbo loans

Investors

  • Investment property loans
  • Conventional investment loans
  • Short-term and long-term rentals
  • Foreign national financing
Learn more: Investors

Non-QM loans

  • DSCR loans
  • Bank statement loans
  • P&L loans
  • VOE loans

Refinance

  • Rate and term refinance
  • Cash-out refinance
  • Streamline refinance

Availability, eligibility and requirements vary by program, property and location. Not all applicants will qualify.

First-time homebuyers

Down payment assistance for your first home.

Assistance programs can lower the cash you need to buy. I compare your options with and without assistance, so you can see the difference before you choose.

  • State and local programs

    Housing finance agencies, and some cities and towns, offer assistance to eligible buyers, including in Massachusetts and Florida.

  • Help with down payment and closing costs

    Depending on the program, assistance may come as a grant or as a second loan that is deferred or forgivable.

  • Paired with your first mortgage

    Assistance usually works alongside an FHA, conventional or other low down payment loan.

  • Homebuyer education

    Many programs ask you to complete a homebuyer education course first. I'll help you find the right one.

Eligibility, income limits, purchase price limits and available funds vary by program and location, and assistance is not guaranteed.

Real estate investors

Financing built for investors.

From your first rental to a growing portfolio, we look at the property's numbers and your goals together.

  • DSCR loans

    Qualify based on the property's rental income rather than your personal income.

  • Conventional investment loans

    For investors who qualify with documented income, on 1 to 4 unit rental properties.

  • Short-term and long-term rentals

    Options for vacation rentals and for long-term tenants. How rental income is counted varies by program.

  • Foreign national financing

    Options for non-U.S. residents buying investment property in the U.S.

  • Self-employed investors

    Bank statement and P&L loans for income that doesn't show up neatly on a W-2.

  • Cash-out refinance

    Use the equity in a property you own toward your next purchase, within program limits.

Investment property programs have their own reserve, credit and property requirements, and terms vary by program.

Build or renovate

Building a home starts with the right blueprint.

Whether you're building from the ground up or buying a new home from a builder, the financing needs a plan before the first shovel.

  • Construction-to-permanent loans

    One loan can cover the construction phase and then become your long-term mortgage, so you close once.

  • Buying new construction

    Financing for a home a builder is completing, with timing planned around the build schedule.

  • Renovation loans

    Some programs let you finance a purchase or refinance together with the cost of repairs or improvements.

  • Builders, budgets and timelines

    We review the builder, the budget and the draw schedule early, because the lender reviews them too.

Construction and renovation programs have their own builder, property and documentation requirements, and availability varies by state.

From blueprint to keys.

Each stage has a purpose. You'll know what we're working toward and what comes next.

  1. Discover

    We talk about your goals, your timeline, and the property you have in mind. Bring your questions.

  2. Design the plan

    We explore financing options and discuss the documentation and requirements relevant to your situation.

  3. Build the file

    We work through your documents, coordinate the review, and keep you informed as underwriting progresses.

  4. Hand over the keys

    If approved, we help you prepare for closing and understand the final steps toward your property.

languages · English & Spanish
2
steps from blueprint to keys
4
states · through our team
50

Frequently asked questions

A little context before we talk. These answers are general education; requirements depend on the program and your circumstances.

What is a DSCR loan?

A debt service coverage ratio, or DSCR, loan is a type of investment property financing that considers the property's rental income in relation to its debt obligations. How rental income is evaluated and what documentation is required depend on the program. We can discuss whether this approach may fit the property you're considering.

Can foreign nationals get a mortgage in the U.S.?

Financing programs may be available for non-U.S. residents purchasing U.S. property. Eligibility depends on the program, property, and borrower circumstances. We can review the general documentation requirements and discuss potential options for your situation.

I'm a first-time buyer. Where do I start?

Start with a conversation about your goals, timeline, and financial picture. We'll discuss the process, the documents typically requested, and the financing options you may be eligible to explore. Down payment assistance programs may be available; eligibility and availability vary.

Can we work together in Spanish?

Yes. Ivan provides service in English and Spanish. Choose the language you feel most comfortable using to ask questions and discuss your financing plan.

Which states do you serve?

Loans available in all 50 states through our team with Michael Mizrahi, NMLS #188831. Available programs and licensing requirements vary by location. Please review NMLS Consumer Access for licensing information and confirm availability for your property when we speak.

Let's design your plan.

Bring your vision and your questions. We'll start with a conversation about what comes next.

Book a call (opens in a new tab)